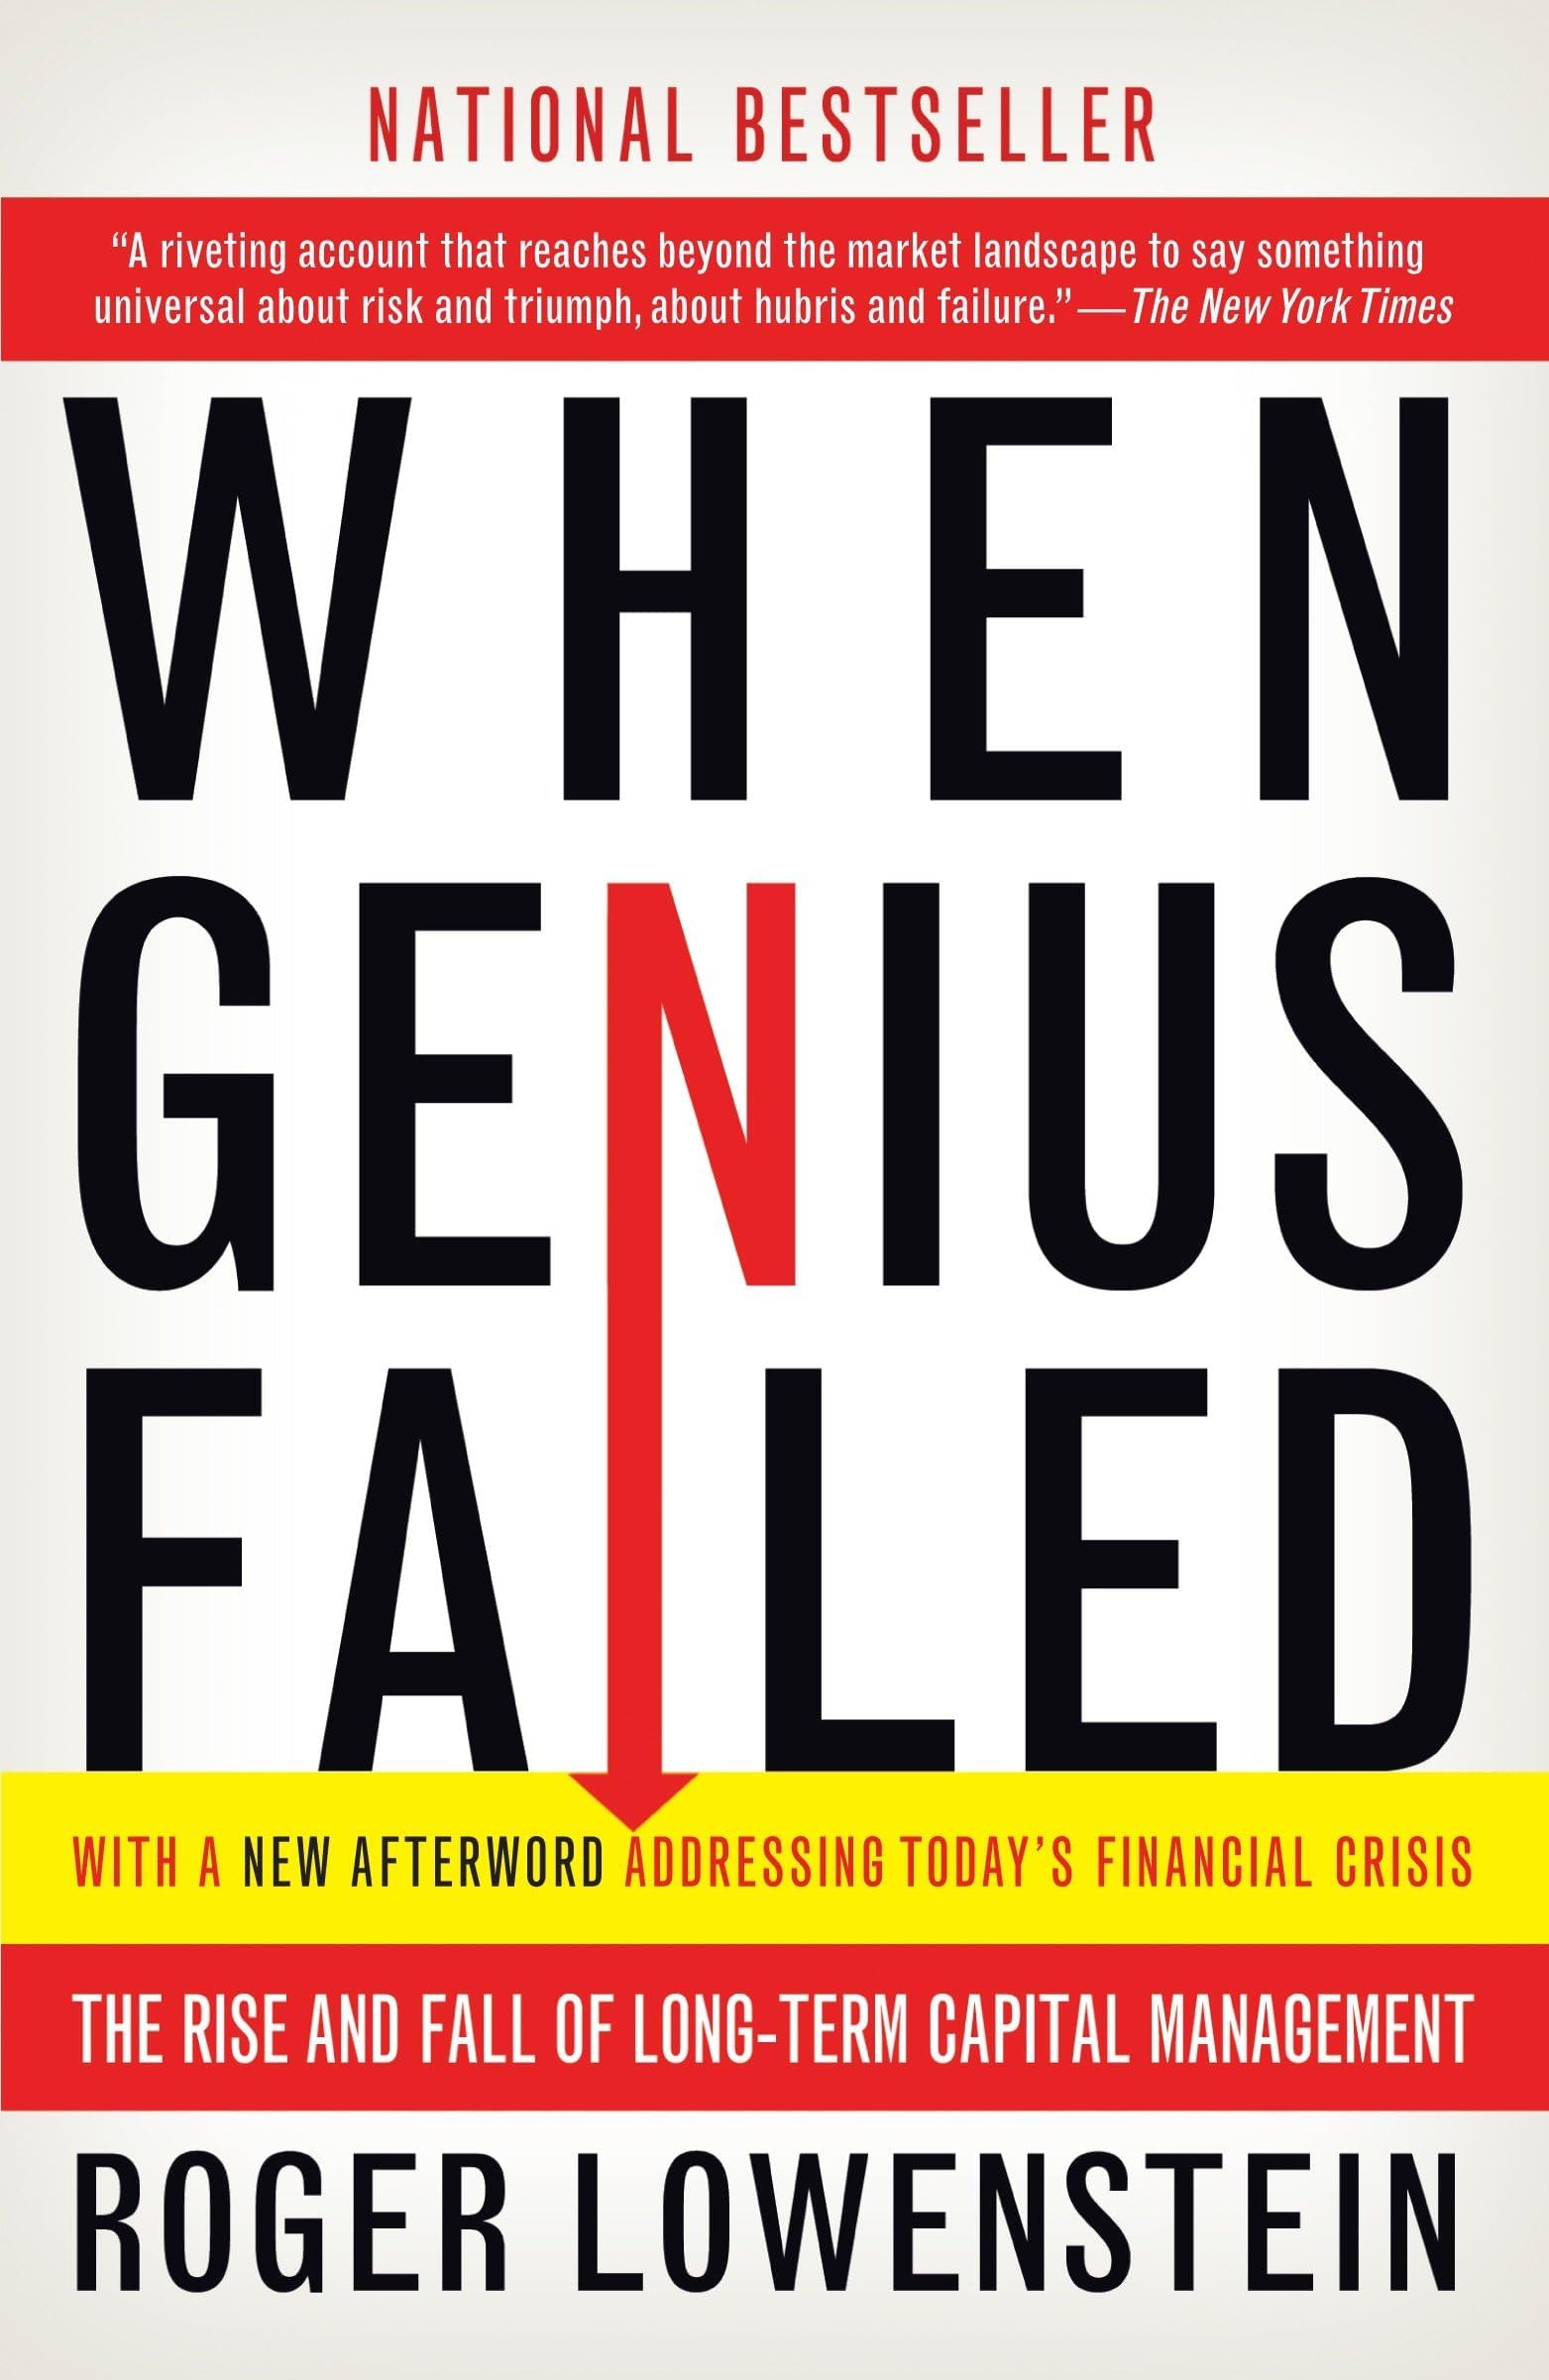
Random House Trade When Genius Failed: The Rise and Fall of Long-Term Capital Management
Desertcart purchases this item on your behalf and handles shipping, customs, and support to Indonesia.
Description
“A riveting account that reaches beyond the market landscape to say something universal about risk and triumph, about hubris and failure.”― The New York Times NAMED ONE O
Specifications
| Dimensions | 13.11 x 1.6 x 20.32 cm |
| Edition | Reprint |
| Isbn 10 | 0375758259 |
| Isbn 13 | 978-0375758256 |
| Item Weight | 1.05 Kilograms |
| Language | English |
| Print Length | 304 pages |
| Publication Date | 9 October 2001 |
| Publisher | Random House Trade Paperbacks |
Reviews
User
Good one
Delivery delayed a bit but product is 100% fine
User
Still very relevant in 2020.
Wonderful example of journalism at its best, with just the right level of detail. Still very relevant more than 20 years since, with the parallels to 2008 (and the “Too Big To Fail”) simply unbelievable.
User
Great narrative on how even the best financial models don't account for the human factor
In this book, Roger Lowenstein presents an excellent detailed narrative of the rise and fall of Long-Term Capital Management. The book is aimed at a layman and does not require understanding of complex financial instruments - but that knowledge makes the story even more intriguing.LTCM was an elite hedge fund started by John Meriwether, the head of the arbitrage group at Salomon Brothers. The fund recruited top professional talent with extensive contacts and, uniquely, top academics from MIT, Harvard, and other universities, including Robert Merton and Myron Scholes, who would later (in 1997) share the Nobel Prize in Economics for developing a model for pricing derivatives, known as the Black-Scholes formula. Led in part by these gentlemen, LTCM had a highly quantitative method to its trading. It started in bond arbitrage, betting that spreads between bonds of similar type would converge, and it achieved fantastic results in the first three years of its operation. So, where did things go wrong?Due to their extensive contacts, LTCM's partners were able to secure unprecedented levels of financing from banks all over Wall Street. Not only was LTCM able to leverage itself highly, but it did so cheaply. All the banks wanted a piece of the action, so LTCM was able to secure very low cost of debt and essentially no haircuts for collateral. This means that LTCM was able to achieve even higher levels of leverage than normally possible.Furthermore, as bond arbitrage opportunities started to melt away due to influx of competitors, LTCM plunged into unexplored waters: merger arbitrage, bets on equities via derivatives, bets in emerging markets, etc. The firm essentially started to shift away from convergence bets to directional bets, which are inherently speculative. In other words, LTCM began to meddle outside its area of expertise.Not only was LTCM highly levered and making risky bets, its partners shared one major flaw: hubris. They whole-heartedly trusted their mathematical models and abstract systems. Merton and Scholes were faithful followers of the efficient market hypothesis and refused to believe in any behavioral finance mumbo-jumbo. Their models predicted that LTCM could not lose a significant amount of capital in any one day. Only a castrophic event, a statistical freak - one in trillions - could cause serious damage to the fund. Even when Eugene Fama, Scholes' thesis advisor, published a paper detailing "fat tails" in the distribution of market returns, Scholes dismissed the idea. Fama demonstrated that the market does not follow a log-normal distribution (as assumed by Black-Scholes) - instead, outlier events such as large market crashes are significantly more likely to occur. Additionally, so confident were the partners in their creation that they did not hesitate to put millions of their own capital into the fund. Usually, when partners put up their own money, they are much more risk averse since their own hard-earned dollars are at stake. LTCM's partners, however, exhibited THAT much confidence in themselves.When Russia defaulted on its debt on August 17, 1998, investors everywhere ran from investment risk in the market, buying up the safest investments - US Treasurys. This widened the swap spreads and raised credit premiums, which went completely against LTCM's positions. Since LTCM was heavily leveraged, its losses were staggering: on August 21st alone, LTCM lost $553 million. In the four hellish weeks that followed, it lost the remaining $2.9 billion of equity. It was unable to unwind its positions, because there were no buyers - liquidity had tried up. Meriwether and his crew attempted to raise capital from anyone and everyone, but no one was interested - rumors of LTCM's losing positions were floating around and scaring off investors that could save the fund.The second half of the book describes the bailout process for LTCM. Goldman Sachs and Warren Buffett attempted to purchase the fund's positions for a miniscule price, all while Goldman was taking advantage of its knowledge of LTCM's trades - it was constantly squeezing LTCM's positions, further lowering the fund's value. Finally, the Fed guided most Wall St banks to a private rescue, in which only one bank refused to participate and later paid the price dearly: Bear Stearns.Lowenstein describes all the events in great detail - he has clearly done a tremendous amount of research. My only gripe is that I often did not feel immersed in the situation. Michael Lewis in his Liar's Poker creates a vivid image of each character and really makes you feel like you're there in the story. This book is more factual and less immersive in a way. But don't get me wrong, that's a minor issue, more of a personal preference.I highly recommend the book to anyone in finance or anyone interested in financial history. The fall of LTCM presents a classic case of what Lowenstein calls the "human factor." At the end of the day, financial models can't predict greed, hubris, and the behavior of various individuals. And no matter how hard you try to diversify, during a crisis, correlation often goes to one.Pros:+ easy read for anyone, even those with little finance knowledge+ great explanation of LTCM's flaws, including a discussion on "fat tails"+ excellent detail on LTCM's strategies and positions+ reminds the reader of a very important point that many finance gurus forget: the human factorCons:- could use a bit more language and imagery to immerse the reader into the story
User
Increible historia, sin duda un must para todo amante del Finance gossip
Excelente libro, muy apegado a los tiempos actuales. Un must para aficionados a la historia de las finanzas.
User
Muy bien escrito !
Entretenido e instructivo
User
分布曲線のの両端が細くなだらかだとは限らない[原書review]
パートナーに2人のノーベル経済学賞受賞者を含む最高の頭脳集団で構成されたヘッジファンドLTCMの劇的な盛衰のドラマを描いた秀逸な作品。アジアの通貨危機、ロシアの債務不履行に翻弄されるパニック状態の市場環境下で、過去のパターンのから未来を予測する数学モデルへの過信とEfficient Market HypothesisやRandom Walkへの盲信(仮説と事実を履き違える)に基づくポジショニングが、ことごとく裏目に出る様子、思惑の異なる主要銀行各行によるLCTM救済への道程の描写は、差し迫った緊迫感が伝わってくる。また、市場は必ずしもrandom walkではない(≒分布曲線の両端が細くなだらかな曲線になっているとは限らない[curve with fat tails])ということを、コイン投げ(1回1回が互いに独立した感情に左右されない行為)とマーケットでの価格形成(記憶や感情を含む)の比較や、riskとuncertaintyを峻別して記述しているChapter 4 “Dear Investors” は統計やファイナンスの基礎的な知識のある読者には興味深いのではないだろうか。
User
Reads Like a Thriller – Hard to Put Down!
I didn't expect a book about a 1990s hedge fund to be this much of a page-turner. Lowenstein has a gift for narrative; he brings the partners of LTCM to life, showing their meteoric rise and the agonizing, day-by-day collapse that followed.The detail is incredible—you feel like you’re in the room during the secret meetings at the Federal Reserve. It’s a fascinating look at the 'culture of genius' on Wall Street and how easily confidence can turn into arrogance. Even if you aren't a 'finance person,' the drama of the story will keep you hooked until the very last page. Highly recommended!
Common Questions
Trustpilot